Based on the selections
Loan-Readiness Assessment
A preparation-focused review before a formal Texas residential financing application.
- Readiness discussion
- Documentation roadmap
- Potential issue identification
- Preparation priorities
 Freedom CapitalManagementRequest a Consultation
Financial guidance to acquire property
Preparation for Texas residential financing requests, DSCR financing for qualifying residential investment properties, and private-money options subject to property and program availability.
Find the right starting point
Choose the goal and current stage. The page will identify the most relevant service and carry that selection into the request form.
Based on the selections
A preparation-focused review before a formal Texas residential financing application.
Four financing paths
Preparation, residential purchase financing, DSCR investor financing, and private money address different needs and transaction stages.
Two connected stages help a borrower prepare before application and organize the information needed for submission.
Financing guidance for first-time and returning residential buyers, including preparation, estimated funds, documentation, and application milestones.
Purchase and refinance financing for qualifying one- to four-unit residential investment properties in eligible states.
Property-focused purchase or refinance options when timing or transaction structure calls for an alternative path.
Investor financing path
DSCR programs generally consider qualifying property rental income in relation to the proposed housing obligation. Property location, reserves, documentation, transaction structure, licensing, program requirements, and underwriting remain part of the review.
Alternative financing path
Private money may provide another path when property, timing, or transaction structure does not fit a conventional residential or DSCR program. The review considers the collateral, location, requested amount, available funds, intended use, transaction terms, and planned repayment or exit strategy.
How the financing process works
The exact requirements depend on the borrower, property, transaction, program, and professional lending relationship.
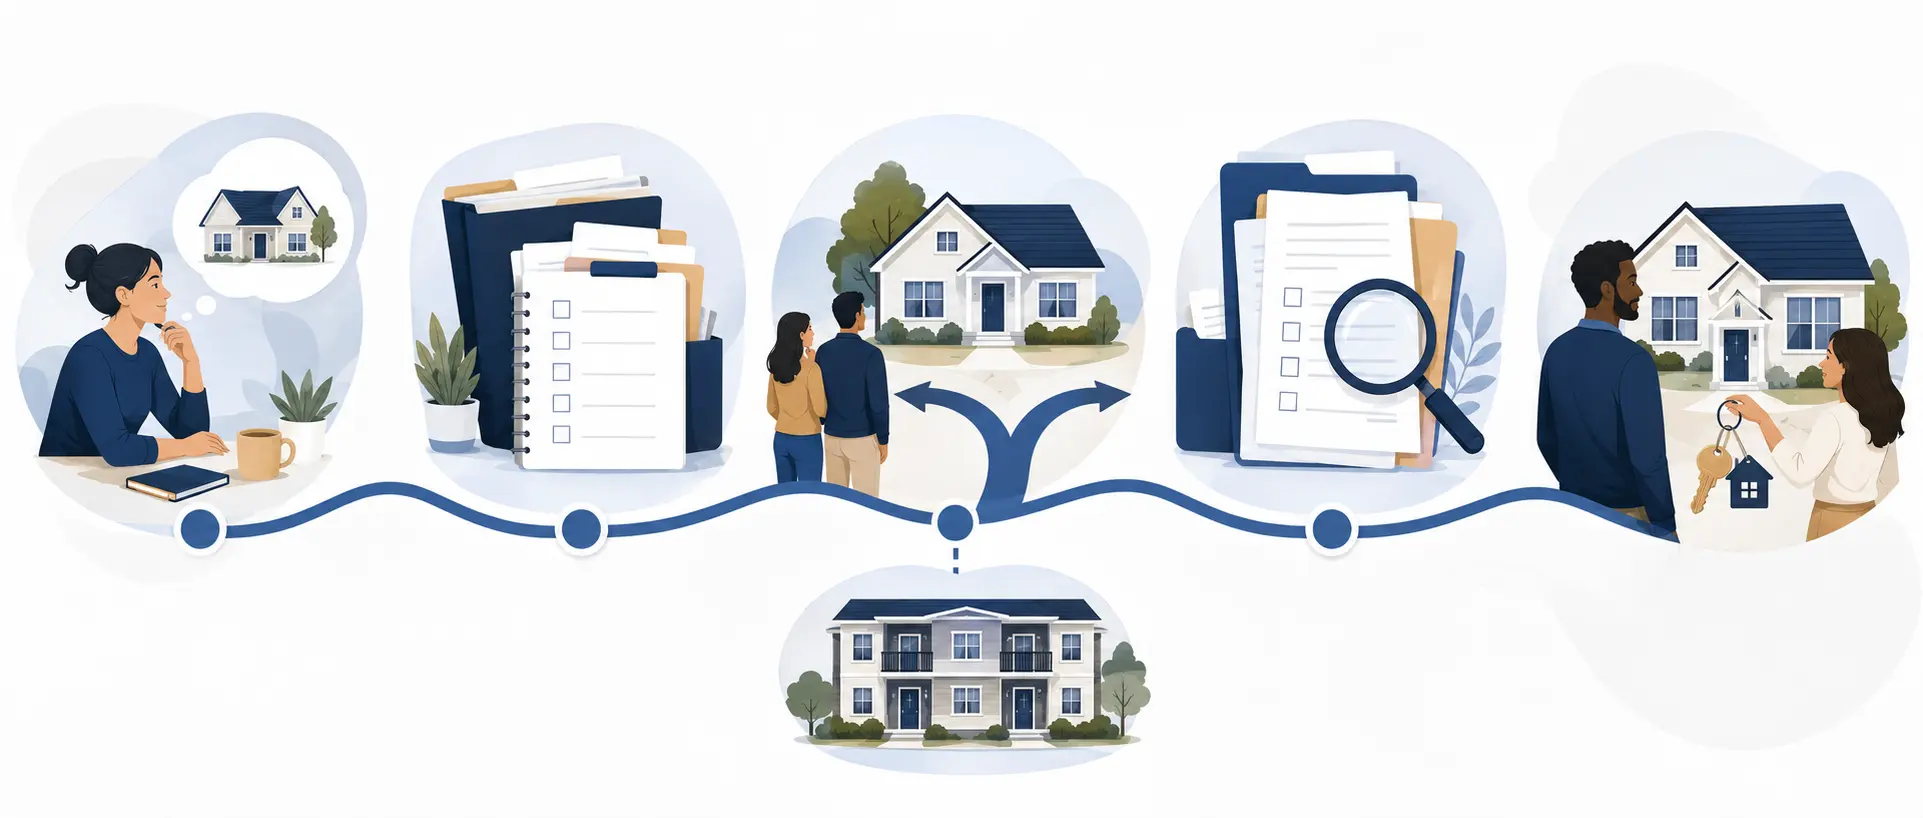
Identify the property use, location, transaction, timing, and available funds.
Organize the borrower, property, income, asset, credit, or rental information needed for the applicable path.
Consider property eligibility, licensing, documentation, program requirements, and transaction structure.
Respond to requests and provide the information needed for review of the borrower, property, and transaction.
Complete the applicable conditions, final documents, and scheduled closing steps.
Prepare with fewer surprises
The exact documents depend on the selected path. These categories provide a practical starting point.
Common questions
No. Preparation helps organize information and identify the appropriate next step. Approval and final terms depend on a completed application, qualification, property review, program requirements, and underwriting.
No. The services described here concern Texas residential financing and DSCR financing for qualifying residential investment properties. Commercial financing is not offered.
DSCR programs may be available for qualifying one- to four-unit residential investment properties. Availability depends on the property location, transaction, program requirements, licensing, and underwriting.
Yes. A readiness or purchase-financing discussion may begin before a property is selected so the borrower can understand preparation, documentation, and the applicable process.
Begin with the financing goal
The selected path and current stage will be carried into the request form.